

Events
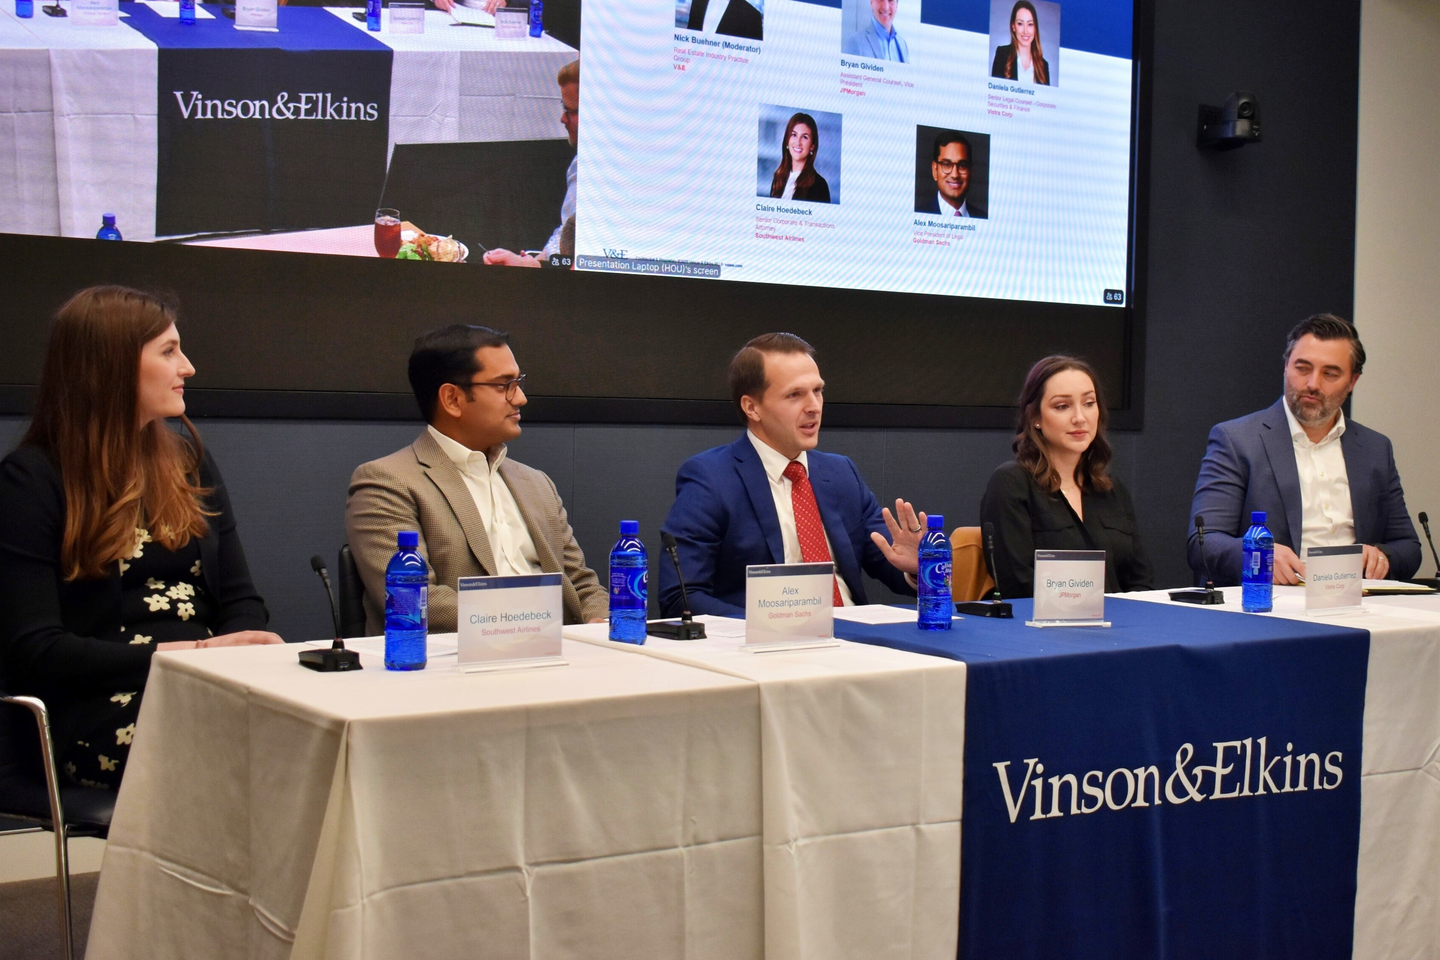
Jenny Speck to Speak at Lockton U.S. Energy Risk Summit
Partner Jenny Speck will speak at Lockton’s U.S. Energy Risk Summit on November 12, 2026, in Houston, Texas. The summit …
November 12, 2026
November 12, 2026 • 1-minute read


Insight
Client Alerts
August 6, 2026 • 3-minute read
On August 5, 2026, the SEC announced a new Financial Reporting and Accounting Unit within its Division of Enforcement. Staffed by both attorneys and accountants, the unit is purpose-built to pursue financial reporting fraud and misconduct in the accounting and auditing space—signaling that these matters will now receive dedicated expertise and focus inside Enforcement.
New Enforcement Director David Woodcock framed the move as part of a broader effort to align staffing with the Division’s core mission and to crack down on bad actors in the accounting and auditing profession. Notably, Woodcock is himself a certified public accountant who practiced at two major accounting firms before entering law. Today’s announcement follows Woodcock’s statement on May 13, 2026 that “as a matter of first principles, my goals are aligned to those of Chairman Atkins: to return the enforcement program back to basics.” Issuers should expect a renewed attention to accounting cases, with closer scrutiny of smaller reporting errors that could point to larger systemic problems.
The new unit will be led by Timothy Zimmerman, a former senior advisor to the Director who joined the SEC in May 2026 after twelve years at an international law firm and a stint as deputy general counsel at a major accounting and professional services firm.
The new unit builds on recent enforcement activity. Earlier this year, the SEC settled charges against a large agricultural, supply chain management, and food processing company, which agreed to pay $40 million to resolve the agency’s investigation into its prior reporting on intersegment sales, without admitting or denying wrongdoing. The SEC found that when the Company’s Nutrition segment was in danger of missing its operating profit forecasts, executives pressured employees to identify adjustments that would shift profit from other business segments into Nutrition to hit its targets. Those adjustments—retroactive rebates and price changes not available to third parties— were alleged to have rendered false the Company’s disclosure that intersegment transactions were recorded at amounts “approximating market.” The case is a reminder that segment-level reporting, intercompany pricing, and the pressure to meet internal targets can all become enforcement exposure, even where consolidated results are unaffected.
The Key Tronic settlement in April 2026 also demonstrates Enforcement’s focus on financial reporting and internal controls. There, the SEC brought nonfraud charges after employees at a contract-manufacturing plant in Oakdale, Minnesota created fictitious work-in-process entries (internally called “Monster Jobs”) to inflate income. A senior vice president knew of and directed parts of the scheme. When the company received an internal complaint on the morning of a scheduled earnings release, it confirmed the allegations within hours, reopened its books, and released earnings that day anyway—over its auditor’s objection. The SEC also noted that the company did not conduct a sufficient materiality analysis prior to releasing earnings. The SEC charged the then-CFO and the senior vice president individually, but imposed no penalty on the company, crediting its self-policing and remediation. The case confirms that the current Commission will bring nonfraud books-and-records actions—and name individuals—even where the dollar amounts are relatively small (roughly $1 million per quarter), no fraud is charged, and the company cooperates.
Today’s announcement, coupled with recent enforcement actions, emphasize that financial reporting and internal accounting controls are again a top priority for SEC Enforcement. The practical implication for public companies is that this is a good moment to revisit disclosure controls, revenue recognition and estimate-heavy accounting areas, auditor communications, and how your teams document key judgments.
If you’d like to discuss how this affects your next 10-Q or 10-K, please reach out to any of us.
This information is provided by Vinson & Elkins LLP for educational and informational purposes only and is not intended, nor should it be construed, as legal advice.
Discover our latest:
Events
Jenny Speck to Speak at Lockton U.S. Energy Risk Summit
Partner Jenny Speck will speak at Lockton’s U.S. Energy Risk Summit on November 12, 2026, in Houston, Texas. The summit …
November 12, 2026
November 12, 2026 • 1-minute read
CLE Events
Sixth Annual Navigating the Annual Meeting and Reporting Season
Join leading practitioners and industry voices for a timely discussion of the legal, regulatory, and governance developments shaping the next proxy season.
November 11, 2026
November 11, 2026 • 2-minute read

Events
Jenny Speck Speaking at 2026 AFCC Global Biobased Economy Conference
Partner Jenny Speck will speak at the 2026 AFCC Global Biobased Economy Conference & Exhibit in a session titled “Tax …
November 3, 2026
November 3, 2026 • 1-minute read

Articles
Executive Order 14421: Managing the Risk of a Ban on Chinese Grid Equipment
The nation’s electric grid depends heavily on foreign-made equipment, much of it from China. Depending on how the Dept. of …
October 30, 2026
October 30, 2026 • 1-minute read

Podcasts
Powering Progress Episode 14 – Environmental Litigation and the New Data Center Playbook
This series has explored the extraordinary investment flowing into data centers and the challenges surrounding power, real estate, financing, and …
October 29, 2026
October 29, 2026 • 14-minute read

Media Coverage
Stephanie Noble Featured in Energy & Mineral Law Foundation Member Spotlight
Partner Stephanie Noble was featured in the Energy & Mineral Law Foundation (EMLF) Member Spotlight, where she discussed her path …
October 28, 2026
October 28, 2026 • 1-minute read

Deals & Cases
Vinson & Elkins advised GridStor in connection with the financing of White Tank, a 100 MW / 400 MWh stand-alone …
October 28, 2026
October 28, 2026 • 1-minute read

Deals & Cases
Vinson & Elkins Advises on Bison Oil & Gas IV’s Inaugural $600 Million Senior Notes Offering
Vinson & Elkins advised the initial purchasers in connection with Bison Oil & Gas IV, LLC’s inaugural private offering of …
October 28, 2026
October 28, 2026 • 1-minute read

Firm News
Vinson & Elkins Hires Corporate Partner Lisa Morales
Morales is an experienced M&A lawyer who advises major public companies, financial institutions, and private capital clients on strategic transactions. …
October 28, 2026
October 28, 2026 • 2-minute read

Deals & Cases
Vinson & Elkins Represents Perella Weinberg Partners as Financial Advisor in EQT Takeover of Qiagen
Vinson & Elkins is representing Perella Weinberg Partners as financial advisor to the Supervisory Board of Qiagen N.V. in connection …
October 22, 2026
October 22, 2026 • 1-minute read

Articles
Law Is a Practice. So Is Business Development.
Randi Revisore, Lauren Alford, and DeAnna Englezos reflect on two years of success leading BD Lab — Vinson & Elkins’ …
July 14, 2026 • V&E+ | Values
July 14, 2026 • 7-minute read
Articles
Data Center Dealmakers: A New Era of Power and Compute
Vinson & Elkins Partners Creighton Smith and Milam Newby share the story behind a groundbreaking AI infrastructure transaction — and …
June 15, 2026 • V&E+ Ventures
June 15, 2026 • 5-minute read

Client Alerts
Mid-Level Mindset: Empowering Lawyers Through a Pivotal Career Stage
Vinson & Elkins’ inaugural Mid-Level Associate Summit brought lawyers from across the firm to Houston for three days of learning …
March 31, 2026
March 31, 2026 • 5-minute read

Client Alerts
Pro Bono at Vinson & Elkins: Lawyers Changing Lives
Pro Bono Counsel Parker Cragg reflects on a life dedicated to service, returning to Vinson & Elkins, and wisdom he has picked up along the way.
October 20, 2025 • V&E+ Values
October 20, 2025 • 6-minute read

Client Alerts
The Genuine Cup: Soccer Strengthens Our Communities
Vinson & Elkins Chair Keith Fullenweider and Vice Chair Hilary Preston, alongside partners Creighton Smith and Jenny Speck, sit down for conversation on a global soccer tournament, the firm’s support for it, and their experience as spectators and volunteers.
August 27, 2025 • V&E+ Values
August 27, 2025 • 7-minute read

Thoughts or questions? Send us a note, and we’ll connect you with the right person.

our People
Please note that any communication with Vinson & Elkins via e-mail through this website does not constitute or create an attorney-client relationship with V&E. Please do not send any confidential information. A conflicts-of-interest procedure must be completed by V&E prior to establishment of an attorney-client relationship. When you execute an engagement letter from V&E you will be our client, and you may then exchange information freely with a V&E attorney.
By clicking “Accept,” you agree that we may review any information you transmit to us. You recognize that our review of your information, even if it is highly confidential and even if it is transmitted in a good faith effort to retain us, does not preclude us from representing another client directly adverse to you, even in a matter where that information could and will be used against you.