

Events
Jenny Speck to Speak at Lockton U.S. Energy Risk Summit
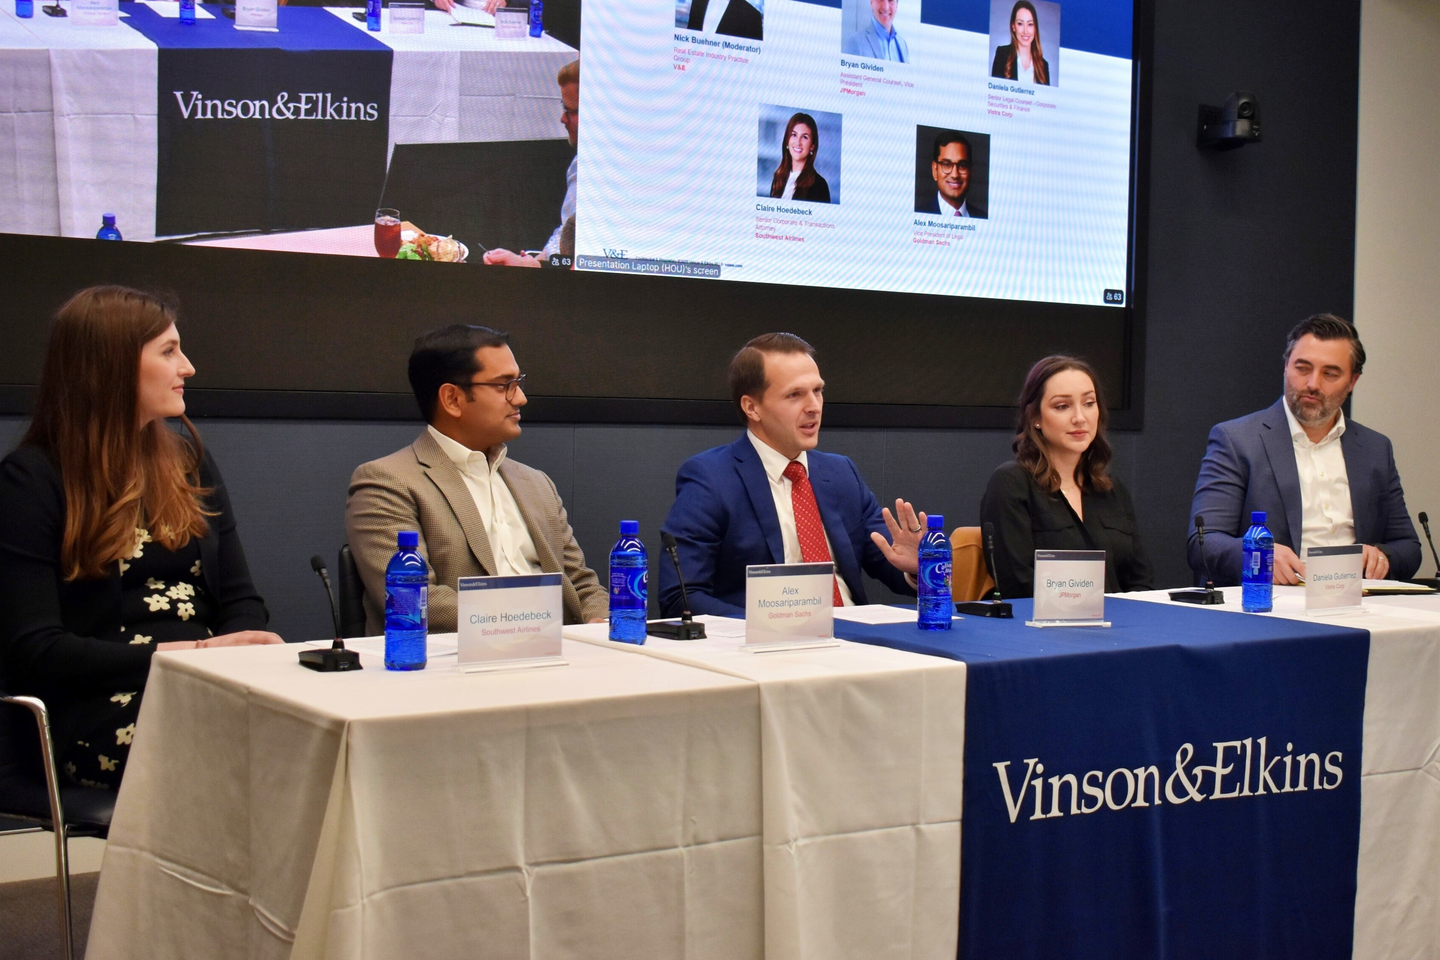
Partner Jenny Speck will speak at Lockton’s U.S. Energy Risk Summit on November 12, 2026, in Houston, Texas. The summit …
November 12, 2026
November 12, 2026 • 1-minute read


Insight
Client Alerts
On June 16, 2025, the Senate Finance Committee released its draft tax title for inclusion in the Senate’s version of the budget reconciliation bill, known as the “One Big Beautiful Bill Act” (the “OBBBA”). While the Senate draft retains many provisions from the House of Representatives’ version, passed on May 22, 2025 (the “House Bill”), there are some notable differences. As the legislative process continues, further modifications to the OBBBA remain possible. This client alert summarizes the key tax provisions in the Senate’s draft (the “Senate Bill”) that are likely to have a substantial impact on real estate investment trusts (“REITs”) and their shareholders, with particular attention to foreign investors.
Permanent Extension of the Qualified Business Income Deduction for REIT Dividends
The Senate Bill would make permanent the current 20% deduction for qualified REIT dividends under Section 199A. This provision, which was originally enacted to provide parity between REITs and other pass-through entities, is currently scheduled to expire for taxable years beginning after December 31, 2025. By eliminating the sunset provision, the Senate Bill would preserve the deduction, and the maximum effective top federal tax rate of 29.6% on ordinary REIT dividends for individuals, trusts, and estates. Notably, the Senate Bill does not increase the deduction percentage to 23%, as proposed in the House Bill, but nonetheless provides long-term certainty for REIT investors by making the 20% deduction permanent.
Retaliatory Tax Measures: New Section 899 and Repeal of Section 892 Exemption
The Senate Bill, consistent with the House Bill, introduces a new Section 899, which would impose retaliatory tax measures on persons from “offending foreign countries” (“OFCs”) that impose “unfair foreign taxes” on U.S. persons or their controlled foreign corporations. The retaliatory taxes would be incremental additional taxes that apply on top of the existing tax rates that would otherwise apply. Section 899 would also repeal the Section 892(a) exemption for foreign governments (including sovereign wealth funds) of such jurisdictions.
Under Section 899, U.S. tax rates imposed on “applicable persons” would increase by 5% in the year following the one-year anniversary of enactment, with additional 5% increases each subsequent year, up to a maximum increase of 15% above the current applicable rate (including treaty rates). “Applicable persons” would include foreign governments of OFCs, non-U.S. individuals and foreign corporations that are tax residents in OFCs, certain non-public foreign corporations majority-owned by such persons, certain foreign private foundations and trusts, and other entities identified by the Secretary of the Treasury as connected to an OFC.
The increased tax rates would apply to:
The Senate Bill differs from the House Bill in that it delays the application of Section 899 until no earlier than January 1, 2027, and limits the maximum increase to 15% above the currently applicable rate, ensuring that treaty investors are not subject to taxes exceeding 15% above their treaty rate. In contrast, the House Bill would have permitted increases up to 20% above the statutory rate, potentially subjecting treaty investors to the same rates as non-treaty investors.
The repeal of the Section 892(a) exemption would subject foreign governments of OFCs (including their sovereign wealth funds) to U.S. tax and withholding on U.S.-source passive income, including REIT dividends, at the generally applicable rates (including the increased rates under Section 899), unless relief is provided by an applicable tax treaty. This change could result in significant new U.S. tax liabilities for sovereign wealth investors from OFCs. However, the Senate Bill retains the exemptions for “portfolio interest” and for FIRPTA gains realized by qualified foreign pension funds, which may continue to provide relief for certain foreign investors.
Business Interest Deduction Limitation (Section 163(j))
Section 163(j) currently limits the deduction for business interest expense to 30% of a taxpayer’s adjusted taxable income. For taxable years beginning before January 1, 2022, adjusted taxable income was calculated without regard to deductions for depreciation, amortization, or depletion (i.e., on an EBITDA basis). Since 2022, the limitation has been based on EBIT, reducing the amount of deductible interest expense.
The Senate Bill proposes to permanently restore the EBITDA-based calculation of adjusted taxable income, thereby increasing the amount of business interest expense that can be deducted. This change would provide a more favorable outcome for taxpayers compared to the current law. Unlike the House Bill, which would sunset this change after five years, the Senate Bill would make the EBITDA approach permanent.
Taxable REIT Subsidiary (“TRS”) Asset Test
The House Bill proposed to increase the limit on the value of securities of TRSs that a REIT may hold from 20% to 25% of the value of its assets, effective for taxable years beginning after December 31, 2025. This adjustment was intended to provide REITs with greater structural flexibility and to ease compliance burdens, particularly for those with significant TRS operations and foreign assets. The Senate Bill, however, does not include this proposal and the current 20% limitation would remain in effect.
The Senate Bill introduces several significant tax provisions that would impact REITs and their shareholders, particularly foreign investors. While some changes are positive, like the permanent extension of the qualified business income deduction for ordinary REIT dividends and the restoration of the EBITDA-based business interest deduction limitation, the introduction of retaliatory tax measures against certain foreign investors and the repeal of the Section 892 exemption for foreign governments of OFCs are likely to be the most consequential changes for REITs. REITs with foreign investors, especially those from OFCs, should carefully consider the potential impact of these provisions on their structures and may want to explore planning opportunities to mitigate increased tax exposure, such as the use of leveraged blocker structures or other tax-efficient vehicles. As the legislative process continues, stakeholders should monitor developments closely and consult with tax advisors regarding the evolving landscape.
This information is provided by Vinson & Elkins LLP for educational and informational purposes only and is not intended, nor should it be construed, as legal advice.
Discover our latest:
Events
Jenny Speck to Speak at Lockton U.S. Energy Risk Summit
Partner Jenny Speck will speak at Lockton’s U.S. Energy Risk Summit on November 12, 2026, in Houston, Texas. The summit …
November 12, 2026
November 12, 2026 • 1-minute read
CLE Events
Sixth Annual Navigating the Annual Meeting and Reporting Season
Join leading practitioners and industry voices for a timely discussion of the legal, regulatory, and governance developments shaping the next proxy season.
November 11, 2026
November 11, 2026 • 2-minute read

Events
Jenny Speck Speaking at 2026 AFCC Global Biobased Economy Conference
Partner Jenny Speck will speak at the 2026 AFCC Global Biobased Economy Conference & Exhibit in a session titled “Tax …
November 3, 2026
November 3, 2026 • 1-minute read

Articles
Executive Order 14421: Managing the Risk of a Ban on Chinese Grid Equipment
The nation’s electric grid depends heavily on foreign-made equipment, much of it from China. Depending on how the Dept. of …
October 30, 2026
October 30, 2026 • 1-minute read

Podcasts
Powering Progress Episode 14 – Environmental Litigation and the New Data Center Playbook
This series has explored the extraordinary investment flowing into data centers and the challenges surrounding power, real estate, financing, and …
October 29, 2026
October 29, 2026 • 14-minute read

Media Coverage
Stephanie Noble Featured in Energy & Mineral Law Foundation Member Spotlight
Partner Stephanie Noble was featured in the Energy & Mineral Law Foundation (EMLF) Member Spotlight, where she discussed her path …
October 28, 2026
October 28, 2026 • 1-minute read

Deals & Cases
Vinson & Elkins advised GridStor in connection with the financing of White Tank, a 100 MW / 400 MWh stand-alone …
October 28, 2026
October 28, 2026 • 1-minute read

Deals & Cases
Vinson & Elkins Advises on Bison Oil & Gas IV’s Inaugural $600 Million Senior Notes Offering
Vinson & Elkins advised the initial purchasers in connection with Bison Oil & Gas IV, LLC’s inaugural private offering of …
October 28, 2026
October 28, 2026 • 1-minute read

Firm News
Vinson & Elkins Hires Corporate Partner Lisa Morales
Morales is an experienced M&A lawyer who advises major public companies, financial institutions, and private capital clients on strategic transactions. …
October 28, 2026
October 28, 2026 • 2-minute read

Deals & Cases
Vinson & Elkins Represents Perella Weinberg Partners as Financial Advisor in EQT Takeover of Qiagen
Vinson & Elkins is representing Perella Weinberg Partners as financial advisor to the Supervisory Board of Qiagen N.V. in connection …
October 22, 2026
October 22, 2026 • 1-minute read

Articles
Law Is a Practice. So Is Business Development.
Randi Revisore, Lauren Alford, and DeAnna Englezos reflect on two years of success leading BD Lab — Vinson & Elkins’ …
July 14, 2026 • V&E+ | Values
July 14, 2026 • 7-minute read
Articles
Data Center Dealmakers: A New Era of Power and Compute
Vinson & Elkins Partners Creighton Smith and Milam Newby share the story behind a groundbreaking AI infrastructure transaction — and …
June 15, 2026 • V&E+ Ventures
June 15, 2026 • 5-minute read

Client Alerts
Mid-Level Mindset: Empowering Lawyers Through a Pivotal Career Stage
Vinson & Elkins’ inaugural Mid-Level Associate Summit brought lawyers from across the firm to Houston for three days of learning …
March 31, 2026
March 31, 2026 • 5-minute read

Client Alerts
Pro Bono at Vinson & Elkins: Lawyers Changing Lives
Pro Bono Counsel Parker Cragg reflects on a life dedicated to service, returning to Vinson & Elkins, and wisdom he has picked up along the way.
October 20, 2025 • V&E+ Values
October 20, 2025 • 6-minute read

Client Alerts
The Genuine Cup: Soccer Strengthens Our Communities
Vinson & Elkins Chair Keith Fullenweider and Vice Chair Hilary Preston, alongside partners Creighton Smith and Jenny Speck, sit down for conversation on a global soccer tournament, the firm’s support for it, and their experience as spectators and volunteers.
August 27, 2025 • V&E+ Values
August 27, 2025 • 7-minute read

Thoughts or questions? Send us a note, and we’ll connect you with the right person.

our People
Please note that any communication with Vinson & Elkins via e-mail through this website does not constitute or create an attorney-client relationship with V&E. Please do not send any confidential information. A conflicts-of-interest procedure must be completed by V&E prior to establishment of an attorney-client relationship. When you execute an engagement letter from V&E you will be our client, and you may then exchange information freely with a V&E attorney.
By clicking “Accept,” you agree that we may review any information you transmit to us. You recognize that our review of your information, even if it is highly confidential and even if it is transmitted in a good faith effort to retain us, does not preclude us from representing another client directly adverse to you, even in a matter where that information could and will be used against you.