











Events
Jenny Speck to Speak on BARBRI Webinar
Partner Jenny Speck will speak on BARBRI’s live video CLE program, “Tax Credit Insurance for Energy Projects: PFE Exclusions, Recapture, …
November 19, 2026
November 19, 2026 • 1-minute read

Insight
Client Alerts
V&E Renewable Energy Update
By Sean Moran, Lauren Collins, Jorge Medina, Jenny Speck, Mary Alexander, Sarah McIntosh, and Trey Frye
January 16, 2025 • 12-minute read
On January 7, 2025, the U.S. Department of the Treasury (the “Treasury”) and the Internal Revenue Service (the “Service”) issued final regulations (T.D. 10024) (the “Final Regulations” and the preamble thereto, the “Preamble”) regarding the clean electricity production tax credit and the clean electricity investment tax credit provided by the Inflation Reduction Act of 2022 (the “IRA”)1 and available under new sections 45Y and 48E, respectively, of the Internal Revenue Code of 1986, as amended (the “Code”). Our prior coverage of the proposed regulations regarding these credits can be found here.
As background, Code sections 45Y (the “Tech Neutral PTC”) and 48E (the “Tech Neutral ITC”) became effective at the beginning of this year (January 1, 2025) and are essentially in lieu of the production tax credit (“PTC”) and investment tax credit (“ITC”) that were previously available under Code sections 45 and 48, respectively.2 The Tech Neutral PTC and Tech Neutral ITC apply to certain clean electricity and energy storage property and provide a production or investment based tax credit for such facilities that have a greenhouse gas (“GHG”) emission rate3 of not greater than zero. The Tech Neutral PTC and Tech Neutral ITC are available for facilities that are placed in service after December 31, 2024, and will begin to phase out over a three-year period in the calendar year following the later of (i) the “applicable year” in which GHG emissions drop at least 25% in the U.S. compared to the GHG emissions during calendar year 2022 or (ii) 2032.
Unlike the former PTC and ITC, Code sections 45Y and 48E take a “tech-neutral approach” — i.e., regardless of the type of facility or technology, a clean electricity or storage facility may be eligible for the Tech Neutral PTC or Tech Neutral ITC so long as the relevant facility is a net generator of electricity (taking into account electricity consumed by the qualified facility) with a GHG emissions rate of not greater than zero.4 For many clean energy facilities (including wind, solar, storage, geothermal and hydropower), it will generally be business as usual (with a few considerations highlighted below); however, more novel technologies and facilities that generate electricity through the combustion or gasification of feedstocks that have not been historically eligible for the PTC or ITC may now be eligible for the Tech Neutral PTC or Tech Neutral ITC if they can demonstrate that the facility has a GHG emissions rate that is not greater than zero. On the other hand, certain technologies, such as renewable natural gas and biogas, that historically were eligible to claim the PTC and ITC may now have a more challenging time qualifying for the Tech Neutral PTC or Tech Neutral ITC.5
In many respects the Final Regulations followed rules in the proposed regulations and existing final ITC regulations with a few important changes and additions. Notably, the Final Regulations provide additional rules and guidelines for the calculation of a facility’s GHG emissions rate and boundaries for performing the lifecycle analysis (“LCA”). As further described below, the Final Regulations also outline a variety of additional updates and clarifications that address many of the open questions from the proposed regulations (e.g., impacts of land use change, market mediated effects, and the treatment of renewable natural gas technology). While a full review of these Final Regulations is beyond the scope of this alert, we have highlighted certain notable items below. Please contact a Vinson & Elkins attorney to discuss specific issues or fact patterns.
The Final Regulations expanded the guidelines for determining a facility’s GHG emissions rate and the methodology for performing an LCA for GHG emissions.6
The Final Regulations explicitly provide that wind, hydropower, marine and hydrokinetic, solar, geothermal, nuclear fission, fusion energy, and certain waste energy recovery properties have a GHG emissions rate of not greater than zero and may be deemed published in the Annual Table.9
For determining the availability of the Tech Neutral PTC or Tech Neutral ITC, qualified facilities can rely on the Annual Table that is in effect when a facility begins construction.
An LCA, in determining the GHG emissions, must take into account:
“Alternative fate” – defined as a set of informed assumptions (e.g., production processes, material outcomes, and market-mediated effects) used to estimate the emissions from the use or disposal of each feedstock were it not for the feedstock’s new use due to the implementation of policy (that is, to produce electricity). The applicable “alternative fate” varies by feedstock:
| Feedstock | Alternative Fate | |
| Landfill gas, wastewater, and coal mine methane | Flaring | |
| Animal Waste | Specific determination derived from the national average of all animal waste management practices (results in a carbon intensity score of -51 g CO2e/megajoule (MJ)) | |
| Fugitive methane from fossil fuel activity (other than coal mining) | Productive use |
“Market-mediated effects” – generally effects from policy interventions and certain other factors (like technological innovations) that alter the availability of, and demand for, marketed goods and activities and their related GHG emissions profiles. These effects include land use changes and shifts in total market demand and supply for input fuels, feedstocks, and related commodities.
Impact of the Tech Neutral PTC and Tech Neutral ITC – Whether the availability of the Tech Neutral PTC and Tech Neutral ITC is expected to result in either additional production of the relevant product or material changes in the supply chain must be considered. If so, the LCA must take into account the impact of the direct and indirect emissions of the additional production or changes in the supply chain.11
Emissions over a 30-year temporal scale, but the spatial scale of the LCA is based on the relevant facts and circumstances; and
Primary products, co-products, byproducts, and waste products (as each is defined in the Final Regulations).
The Final Regulations also provided clarifications and modifications to certain defined terms.
The Final Regulations provide updates for specific technologies –
As of the writing of this alert, a “Congressional Review Act” challenge on the Final Regulations has not been introduced in Congress. But, given the impending change in administration and beginning of the 119th Congress, we will be anxiously paying attention to potential challenges to these Final Regulations or other changes in tax law. Stay tuned for updates.
1 Our full coverage of IRA matters can be found here.
2 While the PTC and ITC will still be available for projects that begin construction prior to January 1, 2025, as described above, the Tech Neutral PTC and Tech Neutral ITC apply to facilities that are placed in service after December 31, 2024. As a result, certain projects/facilities will have the option to choose between the PTC and ITC or Tech Neutral PTC and Tech Neutral ITC.
3 Defined as the amount of GHG emitted into the atmosphere by a facility in the production of electricity, expressed as grams of CO2e per kWH. Code sections 45Y(b)(2)(A) and 48E(b)(3)(B)(ii).
4 In order to get the full credit rate, either (i) the taxpayer must satisfy the prevailing wage and apprenticeship requirements with respect to the construction and applicable alteration and repair of such qualifying facility or eligible facility, (ii) the facility must have a maximum net output of less than one MWac, or (iii) construction of the facility must have begun prior to January 29, 2023.
The credit rate may be increased if the “domestic content requirements” are met or if the qualified facility is located in an “energy community” or “low-income community.” See Code sections 45Y(g)(7), 45Y(g)(11), 48E(a)(3)(A), 48E(a)(3)(B), and 48(e).
5 Nevertheless, many renewable natural gas and biogas technologies may be able to qualify for the Code section 45Z Clean Fuel Production Credit.
6 These rules are largely the same for both the Tech Neutral PTC and Tech Neutral ITC.
7 If a technology or type of facility type is not included in the Annual Table, taxpayers will have to rely on certain LCAs deemed acceptable by Treasury and/or apply for a provisional emissions rate.
8 The first Annual Table is included below:
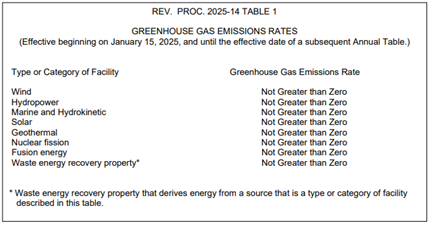
9 While these credits are technology neutral and require a GSG emissions rate of not greater than zero, Treasury and the Service are stipulating that certain technologies clearly have zero GHG emissions and disposed of the need to perform an LCA on such technologies.
10 In order for this change to Tech Neutral ITC and Tech Neutral PTC to promote meaningful innovation, it is critical that a model for LCAs be identified as soon as possible. For example, currently, under Code section 45V, the model is the Department of Energy’s Argonne National Laboratory’s Greenhouse gases, Regulated Emissions, and Energy use in Technologies (“GREET”) model 45VH2-GREET.
11 The Final Regulations provide an example for methane, which describes how the LCA must take into account whether the availability of the Tech Neutral PTC and Tech Neutral ITC may cause the production of additional methane.
12 Compare with 1.48-9(f)(2)(ii); 1.48-9(f)(3).
13 Our previous coverage of the final section 48 ITC regulations can be found here.
14 This is a departure from guidance promulgated under the section 45 PTC which permitted sales to a related party so long as the electricity was resold to a third party (IRS Notice 2008-60).
15 A notable impact of this revision is that certain fuel cell facilities may be treated as combustion or gasification facilities depending on the input energy source.
16 Our previous coverage of the final regulations for the PWA Requirements can be found here.
17 “Integrated operations” of a qualified facility of the same technology type means that the qualified facilities are owned by the same taxpayer or related taxpayers (i.e., members of a group of trades or businesses that are under common control), placed in service in the same taxable year, and transmit electricity generated by the facilities through the same point of interconnection or, if the facilities are not grid-connected or are delivering electricity directly to an end user behind a utility meter, are able to support the same end user.
18 In order to determine the “project” applicable for the PWA Requirements, by cross-reference to Code section 45 and 48 regulations, it appears taxpayers will need to consider the seven-factor test set forth in the final section 48 ITC regulations and any facilities with four or more common factors and shared ownership at certain times will be a single “project.” Whether the taxpayer paid necessary prevailing wage requirements, utilized enough apprenticeship hours, and satisfied recordkeeping and documentation mandates under the PWA Requirements will be determined on this “project” basis.
This information is provided by Vinson & Elkins LLP for educational and informational purposes only and is not intended, nor should it be construed, as legal advice.
Discover our latest:
Events
Jenny Speck to Speak on BARBRI Webinar
Partner Jenny Speck will speak on BARBRI’s live video CLE program, “Tax Credit Insurance for Energy Projects: PFE Exclusions, Recapture, …
November 19, 2026
November 19, 2026 • 1-minute read
Events
Kathy Pakenham and Adriana Wirtz to Speak at TEI’s IRS Roundtable
Partners Kathy Pakenham and Adriana Wirtz will examine how a leaner, more data-driven IRS is selecting and conducting large business …
November 19, 2026
November 19, 2026 • 1-minute read

Client Alerts
Single v Multi Contracts in Nuclear Projects: The Size of the Burden
Introduction The construction of nuclear energy projects is complex and capital-intensive, and the contracting structure can significantly affect project delivery, …
November 13, 2026
November 13, 2026 • 6-minute read

Articles
State Attorneys General Widen the Antitrust Battlefield
State attorneys general are moving to the center of antitrust enforcement, with bipartisan coalitions attacking merger settlements, information-sharing arrangements, labor-market …
November 13, 2026
November 13, 2026 • 4-minute read

Events
Jenny Speck to Speak at Lockton U.S. Energy Risk Summit
Partner Jenny Speck will speak at Lockton’s U.S. Energy Risk Summit on November 12, 2026, in Houston, Texas. The summit …
November 12, 2026
November 12, 2026 • 1-minute read

Thoughts or questions? Send us a note, and we’ll connect you with the right person.


