

Events
Jenny Speck to Speak at Lockton U.S. Energy Risk Summit
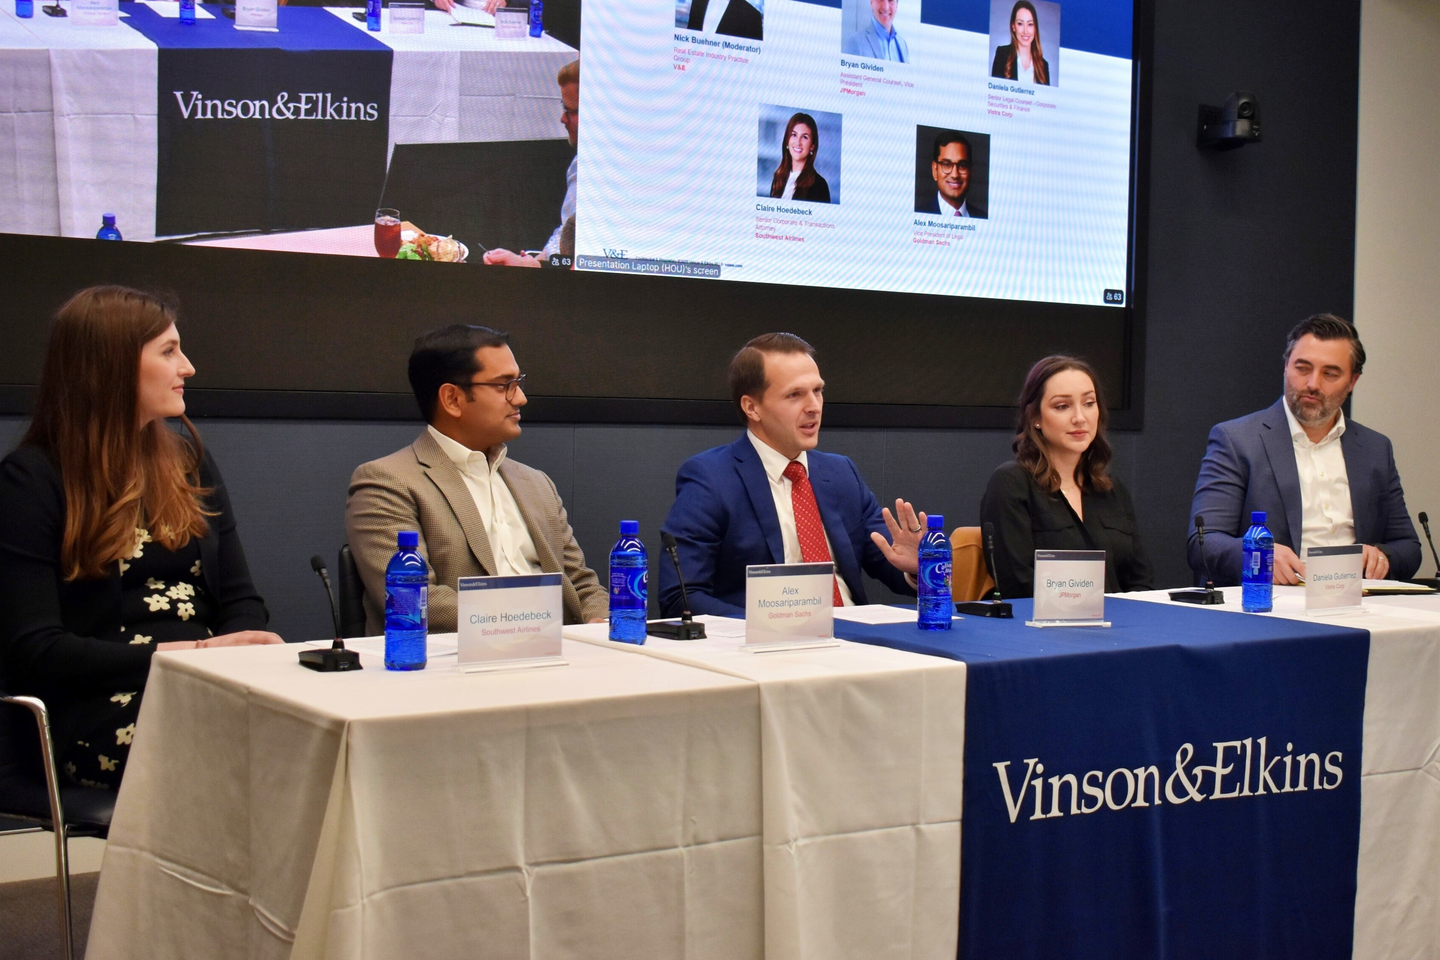
Partner Jenny Speck will speak at Lockton’s U.S. Energy Risk Summit on November 12, 2026, in Houston, Texas. The summit …
November 12, 2026
November 12, 2026 • 1-minute read


Insight
Client Alerts
April 17, 2024 • 4-minute read
Amidst the government’s ongoing efforts to combat insider trading, a recent dismissal of criminal charges for insider trading gives new insight into this constantly evolving area of law. A federal judge recently dismissed criminal charges against eight social media influencers who allegedly ran a $100 million pump-and-dump scheme through their social media accounts.1 In December 2022, both the Securities and Exchange Commission (“SEC”) and the Department of Justice (“DOJ”) brought charges against the influencers for allegedly manipulating the market through coordinated misrepresentations and omissions to their thousands of followers on Twitter and Discord (an instant-messaging social platform). Specifically, the SEC charged the influencers with civil securities fraud under both the Securities Exchange Act of 1934 and the Securities Act of 1933, while the DOJ charged them with criminal securities fraud and conspiracy to commit securities fraud. At the request of the DOJ, the SEC agreed to pause its proceedings so the criminal case could be litigated first.
On March 20, 2024, the United States District Court for the Southern District of Texas, Houston Division (“SDTX”), dismissed the criminal charges levied by the DOJ against all eight defendant influencers. The DOJ had alleged that the influencers engaged (and conspired to engage) in a scheme to maximize their profits via the purchase and sale of certain securities at the expense of their followers by posting false and misleading information and also failing to post other important information on their social media accounts. Essentially, the DOJ alleges the influencers participated in a pump-and-dump scheme by using their followers to artificially increase the price of those securities before secretly selling their own shares. In dismissing the charges, the SDTX applied two recent cases, Ciminelli v. United States2 and United States v. Greenlaw.3
In Ciminelli, the Supreme Court rejected a previously adopted theory of fraud known as the “right to control.” Notably this theory had previously only been applied to wire fraud, however, this did not prevent the SDTX from applying the same framework to securities fraud.4 Under the “right to control” theory, the government could prove that defendants engaged in a “scheme to defraud” victims of “money or property” by showing, among other factors, that the scheme “denies the victim the right to control its assets by depriving it of information necessary to make discretionary economic decisions.”5 But the Supreme Court rejected this theory in Ciminelli, holding that “the so-called ‘right to control’ is not an interest that had ‘long been recognized as property’ when the wire fraud statute was enacted.”6 Furthermore, the Court held the federal fraud statutes are “limited in scope to the protection of property rights.”7 Through its ruling, the Court limited the scope of the wire fraud statute to only apply to schemes that harm a victim’s traditional property right, and not to those that aim to harm a victim’s right to have accurate information.
SDTX also applied Greenlaw, a Fifth Circuit decision holding that the criminal securities fraud statute requires a specific “intent to defraud” and not only a “scheme to defraud.” The court defined “intent to defraud” as requiring both an intent to deceive and an intent to cause some harm to result from that deceit. Specifically, the second prong was defined as an intent to cheat, meaning “to deprive the victim of money or property by means of deception.”8 Moreover, the court suggested that a “scheme to defraud” requires depriving another of money or property and bringing about some financial gain to the defendant.9
Back to Constantinescu, SDTX applied Ciminelli and Greenlaw to find that the DOJ had failed to plead that the influencers had engaged in a “scheme to defraud.” While the court found that the allegations sufficiently asserted that obtaining financial gain was the object of the influencers scheme, the DOJ’s complaint failed to explain how the influencers harmed the victim’s traditional property rights.10 Specifically, the court found that the property right of the investors, harmed by the influencers, was their right to control their assets, or stated another way, was their right to make an informed discretionary decision.11 Thus, the court held that even taking all of the allegations as true, the DOJ failed to state a crime under 18 U.S.C. § 1348 and 2, and 18 U.S.C. § 1349 as interpreted by Ciminelli.12 The final result of the Constantinescu case remains to be seen, as the court granted the influencers’ motion to dismiss without prejudice, leaving room for the DOJ to replead.13 However, given the court’s interpretation and application of Ciminelli and Greenlaw, it may be difficult for the DOJ to plead their case.
Takeaways
Insider trading remains a clear focus of both the SEC and DOJ. In Constantinescu, the SDTX court found that the government must meet a higher standard when pleading fraud, including wire fraud which is often used by the DOJ in cases of securities fraud. It will be interesting to see if other courts follow suit. Moreover, in light of the dismissal, and the potential increased difficulty in pleading criminal securities fraud for the DOJ, the SEC may be less likely to stay its investigations while the DOJ proceeds. As always, we recommend that in-house counsel and compliance professionals consult with attorneys to stay up to date on the latest in this constantly evolving space.
1United States v. Constantinescu, No. 4:22-cr-00612, 2024 WL 1221579, at *5 (S.D. Tex. Mar. 20, 2024).
2Ciminelli v. United States, 598 U.S. 306 (2023).
3United States v. Greenlaw, 84 F.4th 325, 350 (5th Cir. 2023).
4In Greenlaw, the Fifth Circuit noted that a district court’s analysis of the securities fraud statute under Title 18 should be guided by caselaw on the mail and wire fraud statutes under Title 18. Greenlaw, 84 F.4th at 399 n.4.
5United States v. Binday, 804 F.3d 558, 570 (2d Cir. 2015).
6Ciminelli, 598 U.S. at 313.
7Id. at 314.
8Greenlaw, 84 F.4th at 351.
9Id. at 349.
10Constantinescu, No. WL 1221579, at *5.
11Id.
12Id. at *6.
13Id.
This information is provided by Vinson & Elkins LLP for educational and informational purposes only and is not intended, nor should it be construed, as legal advice.
Discover our latest:
Events
Jenny Speck to Speak at Lockton U.S. Energy Risk Summit
Partner Jenny Speck will speak at Lockton’s U.S. Energy Risk Summit on November 12, 2026, in Houston, Texas. The summit …
November 12, 2026
November 12, 2026 • 1-minute read
CLE Events
Sixth Annual Navigating the Annual Meeting and Reporting Season
Join leading practitioners and industry voices for a timely discussion of the legal, regulatory, and governance developments shaping the next proxy season.
November 11, 2026
November 11, 2026 • 2-minute read

Client Alerts
After the Midterms: Preparing for a New Era of Congressional Oversight
Following the November 2026 midterm elections, Democrats will control both the House and the Senate when the 120th Congress convenes …
November 5, 2026
November 5, 2026 • 5-minute read

Client Alerts
Texas Business Court Quarterly Update – 2026 Q3 Summaries
In the third quarter of 2026, the Texas Business Court continued its progress on an ever-growing docket, issuing a number …
November 4, 2026
November 4, 2026 • 44-minute read

Client Alerts
Fifth Circuit Rejects CFIUS Preemption Challenge to Texas’s Lone Star Infrastructure Protection Act
On October 16, 2026, the United States Court of Appeals for the Fifth Circuit issued its decision in GH America …
November 3, 2026
November 3, 2026 • 9-minute read

Deals & Cases
Vinson & Elkins Advises Underwriters on Enterprise Products’ $1.5 Billion Senior Notes Offering
Vinson and Elkins advised the underwriters in connection with Enterprise Products Operating LLC’s (“EPO”) public offering of $1.5 billion aggregate …
November 6, 2026
November 6, 2026 • 1-minute read

Media Coverage
Aubrey Bishai Explains Responsible Vibe Coding and AI Innovation in Law.com
Vinson & Elkins Chief Innovation Officer Aubrey Bishai was featured in Law.com’s coverage of LegalTech Connect’s 2026 Knowledge Management & …
November 5, 2026
November 5, 2026 • 1-minute read

Deals & Cases
Vinson & Elkins Advises Southern Realty Trust Inc. in Merger with Sunrise Realty Trust, Inc.
Vinson & Elkins advised Southern Realty Trust Inc. in connection with its entry into a definitive merger agreement with Sunrise …
November 5, 2026
November 5, 2026 • 1-minute read

Deals & Cases
Vinson & Elkins represented Select Water Holdings LLC, a subsidiary of Select Water Solutions, Inc., in connection with a new …
November 4, 2026
November 4, 2026 • 1-minute read

Deals & Cases
Vinson and Elkins advised Atlas Energy Solutions ProjectCo, LLC in a $424 million committed senior secured bridge facility with Goldman …
November 3, 2026
November 3, 2026 • 1-minute read

Articles
Innovation and Investment: The Next Frontier in Aerospace and Defense
Vinson & Elkins Partners Sebastian Tiller and Ben Heriaud sit down for a conversation on the firm’s Aerospace and Defense …
November 3, 2026
November 3, 2026 • 6-minute read

Articles
Law Is a Practice. So Is Business Development.
Randi Revisore, Lauren Alford, and DeAnna Englezos reflect on two years of success leading BD Lab — Vinson & Elkins’ …
July 14, 2026 • V&E+ | Values
July 14, 2026 • 7-minute read
Articles
Data Center Dealmakers: A New Era of Power and Compute
Vinson & Elkins Partners Creighton Smith and Milam Newby share the story behind a groundbreaking AI infrastructure transaction — and …
June 15, 2026 • V&E+ Ventures
June 15, 2026 • 5-minute read

Client Alerts
Mid-Level Mindset: Empowering Lawyers Through a Pivotal Career Stage
Vinson & Elkins’ inaugural Mid-Level Associate Summit brought lawyers from across the firm to Houston for three days of learning …
March 31, 2026
March 31, 2026 • 5-minute read

Client Alerts
Pro Bono at Vinson & Elkins: Lawyers Changing Lives
Pro Bono Counsel Parker Cragg reflects on a life dedicated to service, returning to Vinson & Elkins, and wisdom he has picked up along the way.
October 20, 2025 • V&E+ Values
October 20, 2025 • 6-minute read

Thoughts or questions? Send us a note, and we’ll connect you with the right person.

our People
Please note that any communication with Vinson & Elkins via e-mail through this website does not constitute or create an attorney-client relationship with V&E. Please do not send any confidential information. A conflicts-of-interest procedure must be completed by V&E prior to establishment of an attorney-client relationship. When you execute an engagement letter from V&E you will be our client, and you may then exchange information freely with a V&E attorney.
By clicking “Accept,” you agree that we may review any information you transmit to us. You recognize that our review of your information, even if it is highly confidential and even if it is transmitted in a good faith effort to retain us, does not preclude us from representing another client directly adverse to you, even in a matter where that information could and will be used against you.